Laplace Distribution
Definition
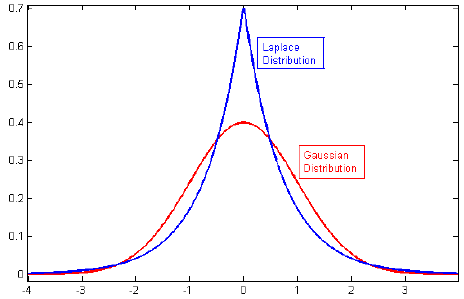
Characterized by its sharp peak and fatter tails (compared to the Gaussian Distribution).
The probability density function is given by:
\[
f(x|\mu, b) = \frac{1}{2b}\exp\left( -\frac{|x-\mu|}{b} \right)
\]
\(\mu\) is the location parameter (the mean, median and mode of the distribution) b is the scale parameter (the spread of the distribution) \(x\) is the random variable
Properties
Symmetric around \(\mu\) The variance is equal to \(2b^2\) Heavier tails, which implies that it assigns higher probabilities to extreme values.
Use Cases
Machine Learning: used in ℓ1 Regularization to encourage sparsity in models.